Tell us what happened
Answer a few short questions and tell your story from wherever you are. Your answers go straight to the team, and sending them commits you to nothing.
Total-loss fights, denied home claims, and the appraisal clause most people never use.
Each step protects the next. Get medical care fast, open the claim on time, build the record, and settle once the record is complete.
Michigan's mini-tort lets you recover up to the statutory cap from an at-fault driver for vehicle damage your own coverage does not pay. Total-loss valuations are their own fight: insurers value your car with software built to run low, and the valuation can be challenged with real comparables.
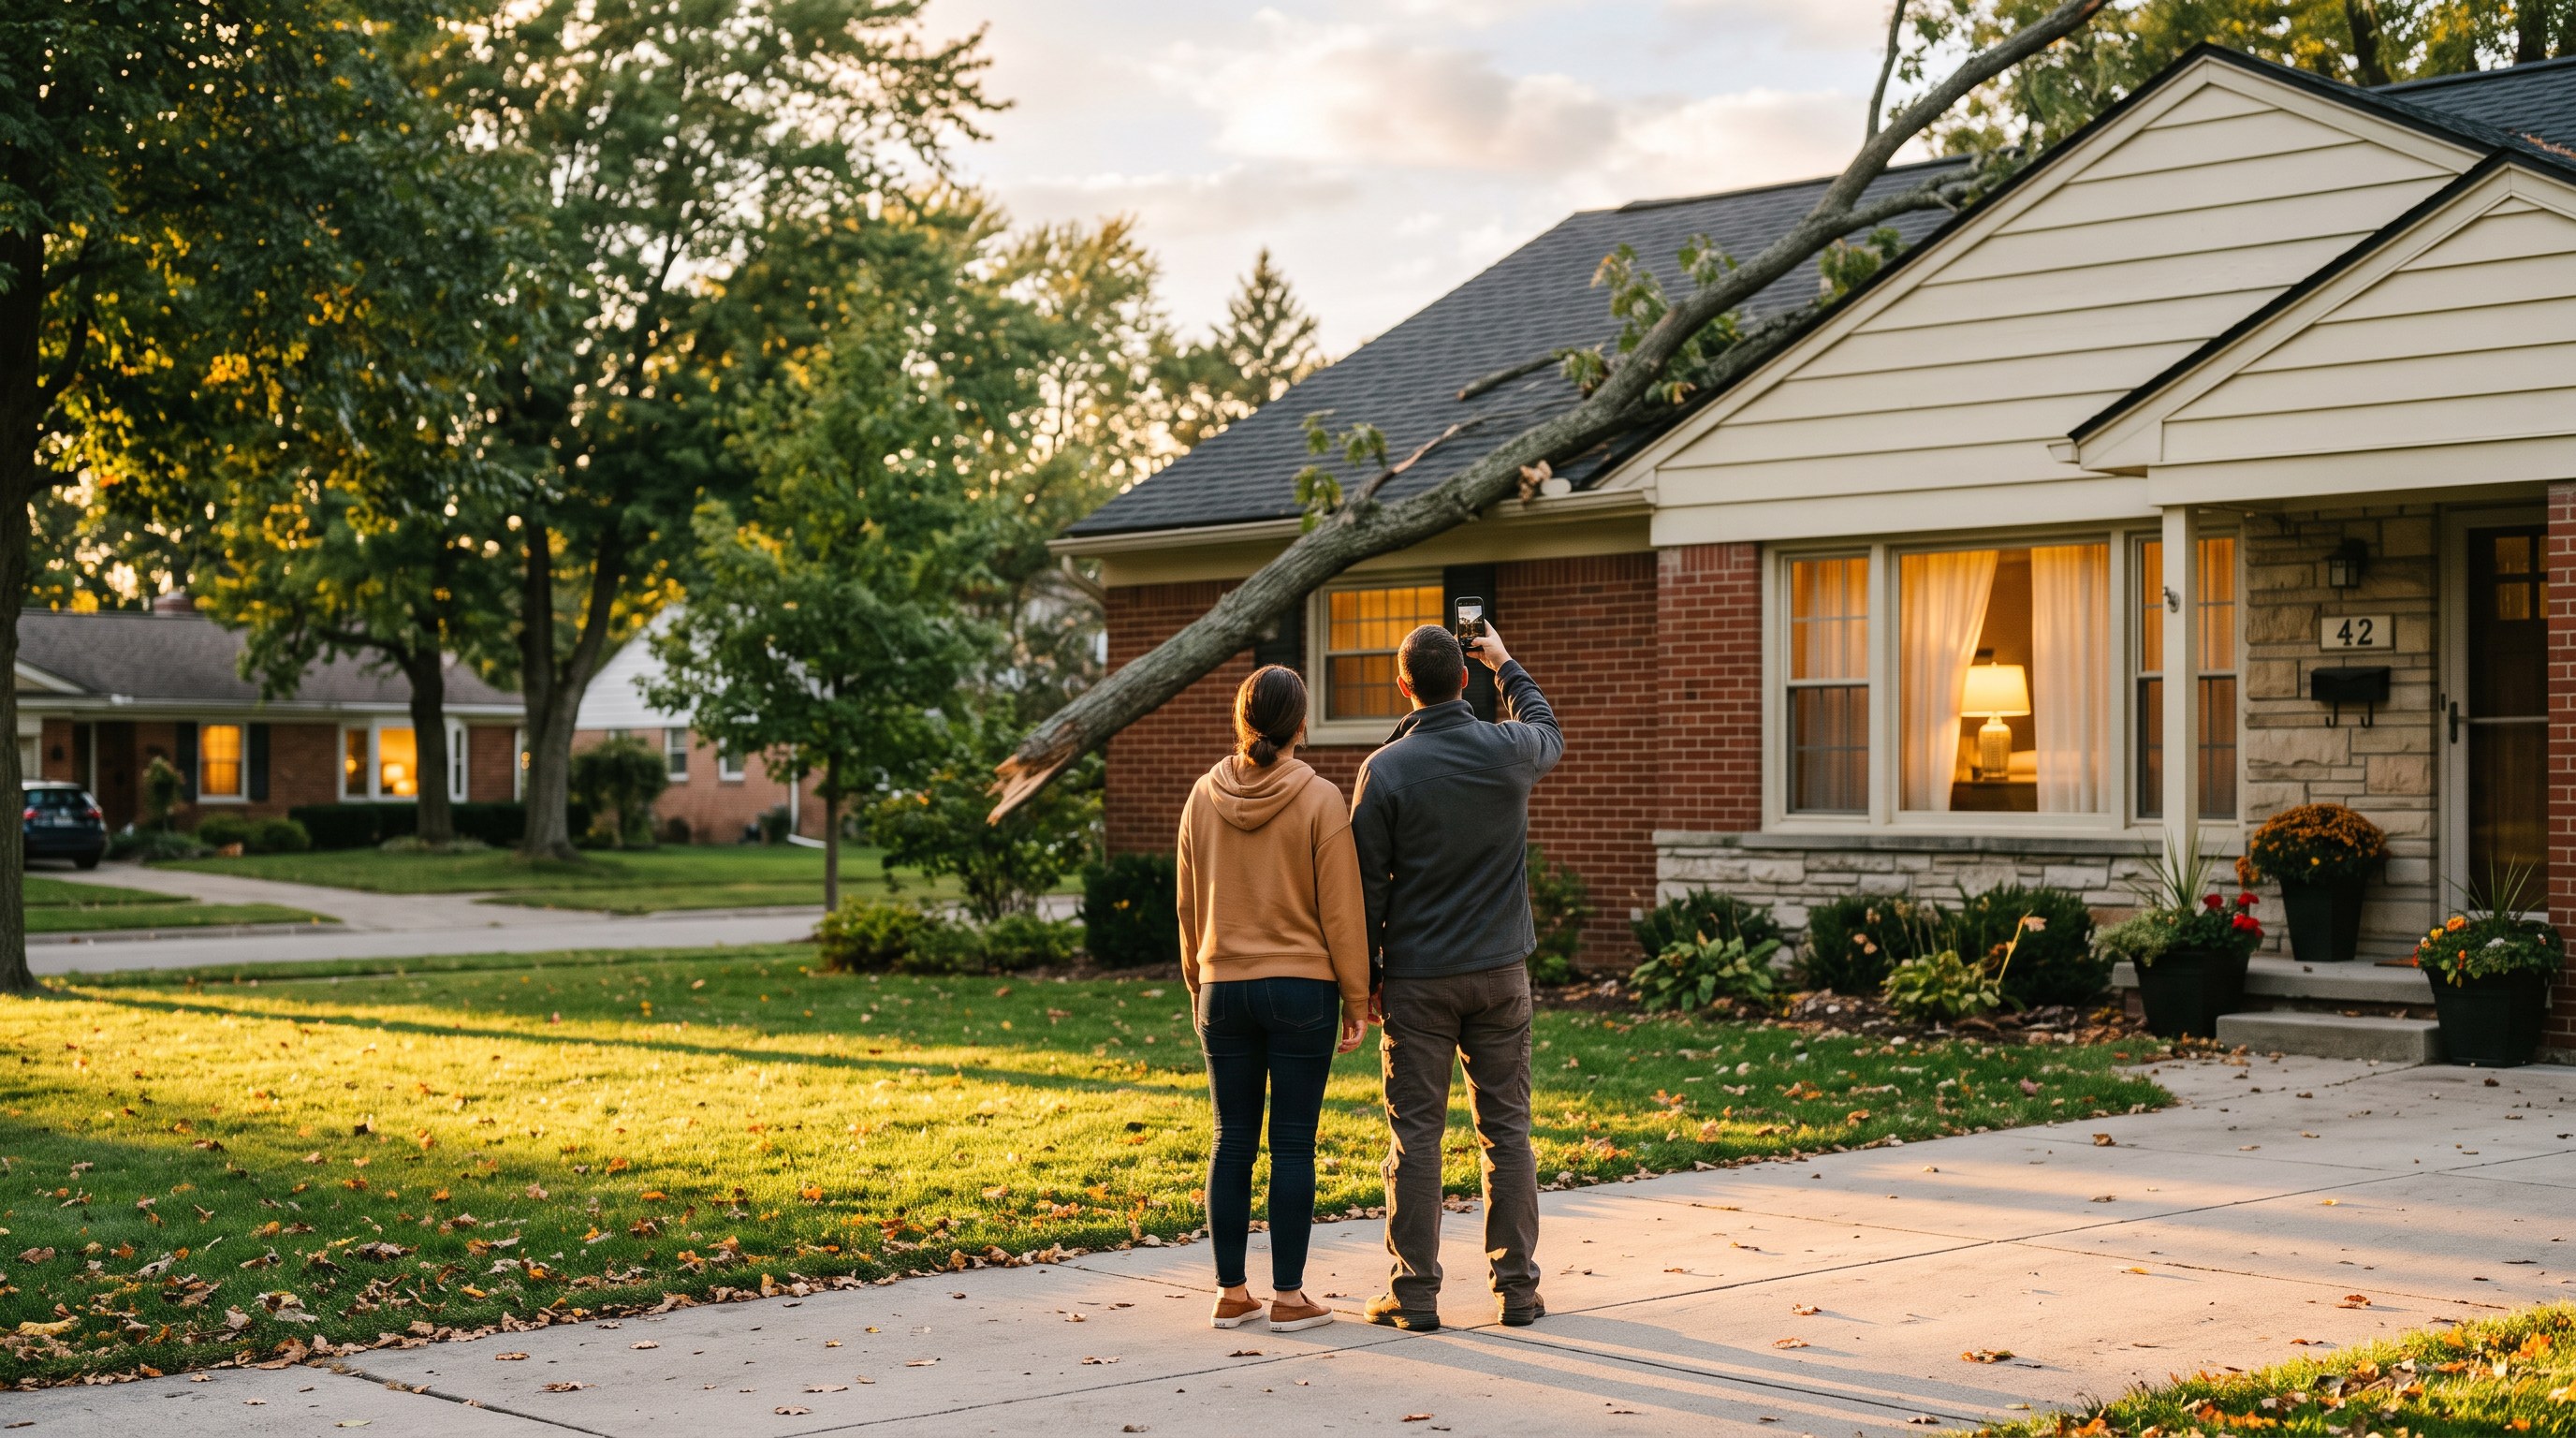
A homeowners policy is a contract. Fire, water, storm, and theft claims get denied or underpaid on exclusions and valuations that do not always survive scrutiny. Read the denial letter for the specific exclusion cited, then read your policy's version of it. They do not always match.
Most policies contain an appraisal clause almost nobody uses: a process where each side names an appraiser and disputes over value get resolved without a lawsuit. It is often the fastest lever on an underpaid claim, and suit remains available when appraisal fails.
Sometimes no. Some property claims are too small for a lawyer to improve after fees. For those we point you to small claims court or the appraisal process and explain how to use each. The consultation is free either way, and fee structure is case-by-case, stated upfront.

Every injury claim in Michigan has deadlines that start the day you are hurt. The forms are short. Missing a date can end the claim.
Time from the crash to each cutoff. The facts of your case can shift these dates. A consultation confirms which ones apply to you.
Economic damages are added up from bills, receipts and lost pay. Pain and suffering has no formula. Each side argues a number from your medical record, and the multipliers you see online have no force in a Michigan court.
Reported contributing factors, statewide. The other driver's behavior is often the heart of the fault argument.
Source: Michigan State Police 2024 year-end crash data.
Yes. Insurers value your car with software built to run low, and the valuation can be challenged with real comparables. The mini-tort also lets you recover up to the statutory cap from an at-fault driver for damage your own coverage does not pay.
A process in most policies where each side names an appraiser and disputes over value get resolved without a lawsuit. It is often the fastest lever on an underpaid claim, and suit remains available when appraisal fails.
Sometimes yes. Some property claims are too small for a lawyer to improve after fees. For those we point you to small claims court or the appraisal process and explain how to use each. The consultation is free either way.
The law here has been quiet. The newest of these seven decisions is from 2015, and together they still decide who pays when a vehicle is wrecked, a house is hit, or an insurer holds back depreciation. What each court held, newest first. We update this section if a new ruling changes it.
July 28, 2026
Most people never see the rules behind a property damage claim until their car is wrecked or something hits their house. The mini-tort. Property protection insurance. An appraisal clause buried in a homeowners policy. Michigan courts drew hard lines on all three, and the lines have held. The newest of the seven decisions below is from 2015, and they still decide these claims. Newest first, with what each court held.
Michigan Court of Appeals, decided October 27, 2015, 313 Mich App 94; 880 NW2d 327
A 1966 Corvette sat in a commercial storage unit. The owner's son and a friend went to flush the fuel lines. Gasoline vapors ignited. The fire destroyed more than $125,000 of personal property belonging to two other people who rented space in the same building. Their fire insurer paid them, then went looking for a no-fault insurer to cover the loss as property protection benefits.
The Court of Appeals held the auto insurer owed nothing. Under MCL 500.3101(1), an owner need not carry no-fault security on a vehicle that is not driven or moved on a highway, and the insurer may let that owner swap the required coverage for comprehensive coverage. The Corvette had not been on a road. When coverage is not mandatory, the court held, the policy language decides. This policy charged no premium for the Corvette and did not cover it.
The court added a footnote that matters. If the two men had driven the Corvette somewhere else to do the work, property protection coverage would no longer have been optional. Where a vehicle sits, and whether anyone moved it, can decide which insurer pays.
Michigan Court of Appeals, decided July 21, 2015, 311 Mich App 442; 875 NW2d 250
Leonard Poll lost control of his mother's Lincoln in September 2011 and crashed into a home in Caledonia. The damage was extensive. Frankenmuth, the homeowners insurer, paid the homeowner $108,260.42. Then it filed a subrogation action against the car's insurer to get that money back.
The court affirmed judgment for the auto insurer. The mother's policy carried a named-driver exclusion naming Poll specifically, which MCL 500.3009(2) permits. The policy warned that when a named excluded person operates the vehicle, all liability coverage is void and the vehicle counts as uninsured under the no-fault statute. The court walked through the three-part property protection test from Turner v Auto Club Ins Ass'n and held the exclusion defeated the claim anyway.
The lesson is about who carries the cost. The homeowner got paid by her own insurer. The attempt to shift that payment to the car's insurer failed on one exclusion.
Michigan Supreme Court, decided November 18, 2014, 497 Mich 1; 857 NW2d 247
Fire damaged a home and much of what was inside it. The homeowner and her insurer settled the dwelling loss but could not agree on the personal property. They invoked the policy's appraisal provision, which MCL 500.2833(1)(m) requires fire policies to include. The umpire's award listed three numbers. Full cost of repair or replacement of $167,923.60. Depreciation of $39,673.48. Actual cash value of $128,250.12. The insurer paid the actual cash value and refused the depreciation because the homeowner had not shown she actually replaced anything.
The Supreme Court reversed the Court of Appeals and held she was entitled to actual cash value only. The award said the appraisers were determining the actual cash value, so that is what it determined. The Court explained the division of labor. Appraisers set the method and the amount of the loss, and that part is conclusive, with review limited to bad faith, fraud, misconduct, or manifest mistake. Courts decide questions of coverage. The policy's replacement cost provision was a condition precedent requiring proof of actual repair or replacement, and MCL 500.2826 authorizes that condition. Because she had not met it, the policy terms controlled.
Anyone holding a replacement cost policy should read that carefully. The Court held an appraisal fixes how much the loss is worth. It does not override a policy term holding back depreciation until you repair or replace.
Michigan Court of Appeals, decided April 4, 2000, 239 Mich App 443; 608 NW2d 519
Two tractor-trailers collided in Battle Creek. A claims specialist for one truck's insurer negotiated a property damage subrogation demand down from $52,000 to $46,800 and paid it in December 1996. Months later someone at the company realized the crash happened in Michigan, where the no-fault act capped tort liability for damage to another vehicle at $500 at the time. The adjuster testified it never crossed his mind the loss occurred in Michigan.
The court confirmed the statutory limit and held the insurer had shown enough evidence of a mistake of fact to survive the other side's motion. It reversed the ruling in the payer's favor, though, because a factfinder could conclude the adjuster knew where the crash happened and simply misunderstood Michigan law. A mistake of law is usually not a ground for getting money back.
Michigan still caps what you recover from an at-fault driver for vehicle damage under the mini-tort, but the number has moved twice since this case. The $500 ceiling is long gone. Under MCL 500.3135(3)(e), the cap is $3,000 for crashes that happened after July 1, 2020. Out-of-state adjusters still get the rule wrong.
Michigan Court of Appeals, decided May 21, 1991, 189 Mich App 485; 474 NW2d 131
A driver pulled a tractor-trailer onto the shoulder of westbound I-96 near Wixom at 2:30 in the morning to read a map. He set the brakes, left his lights and flashers on, and kept the engine running. His tires sat about eighteen inches off the solid white line. Two minutes later a car struck the rear of the trailer and burst into flames.
The court affirmed that the car's insurer owed property protection benefits. Under MCL 500.3121 and MCL 500.3123(1)(a), the insurer of a moving vehicle that collides with a parked vehicle pays those benefits without regard to fault, for damage to the vehicle and its contents. The no-fault act does not define "parked," so the court applied the Vehicle Code definition at MCL 257.38 along with the ordinary dictionary meaning. A vehicle is parked when it has been brought to a stop and stands at the edge of a highway. This truck counted, even with the engine running and the driver in the cab.
The court also affirmed the denial of attorney fees. It held the insurer's refusal to pay was not unreasonable because there was a legitimate question about what "parked" meant.
Michigan Court of Appeals, decided April 15, 1991, 188 Mich App 495; 470 NW2d 88
Kaiser and Smith crashed in June 1988. Sixteen days later Kaiser filed a small claims mini-tort case for damage to her vehicle and won $200 plus $15.50 in costs. The following April she sued in Jackson Circuit Court for noneconomic loss from her injuries. Smith moved to dismiss, arguing she was required to bring both claims together.
The court reversed the dismissal. It held the compulsory joinder rule at MCR 2.203(A) does not apply to small claims division actions, which run under Chapter 84 of the Revised Judicature Act and subchapter 4.300 of the court rules. Neither requires joinder. The court also pointed to the mini-tort provision, now MCL 500.3135(4)(d), which says a mini-tort decision is not res judicata as to other liability from the same circumstances. The Legislature built a separate cause of action for small vehicle damage claims and expected successive actions.
Michigan Court of Appeals, decided March 18, 1986, 150 Mich App 61; 388 NW2d 305
Marilyn Swacker's car collided with a motorcycle owned by Nancy Nerat and driven by Nerat's son. Swacker got a citation for running a stop sign. Nerat carried no collision coverage on the motorcycle, so she filed a small claims case for the $228.85 it cost to repair it and won.
The Court of Appeals reversed. The mini-tort provision creates an exception to the abolition of tort liability only for damages to "motor vehicles," and the no-fault definition, now MCL 500.3101(3)(i), expressly excludes motorcycles from that definition. The court found no ambiguity and held there is no right to sue for motorcycle damage under the mini-tort. What the vehicle is matters as much as who caused the crash.
These decisions describe how Michigan courts have read the statutes and the policy language in front of them. They do not tell you how your own claim will come out, because your facts and your policy control that. If you are staring at a wrecked vehicle, a denied property claim, or an appraisal you cannot make sense of, call Azzo Law at 844-ASK-AZZO (844-275-2996). Intake will take your information and route your question to the right person at the firm.
Lauren Sitto Azzo, lead attorney at Azzo Law, PLLC, is responsible for the content of this page. This section is general information about Michigan court decisions and not legal advice, and reading it does not create an attorney-client relationship.
Tell us what happened, online or at 844-ASK-AZZO. Your attorney calls you back, usually the same day. If your case is not worth pursuing, we say so and tell you what to do instead.
Tell us what happenedOr call 844-ASK-AZZO (844-275-2996) · Free consultation, no fee unless we win on personal injury cases
We use cookies that make this site work, including live chat. Accept also turns on the Google tools that measure how people use this site and how our advertising performs. Essential only keeps those off. Our Privacy Policy has the detail.


