Denied property claims

Property damage

A denial letter is an opening position, not a verdict.

If your insurance company denied or underpaid a claim on your home, your car, or your belongings, you can push back. Bring us the denial letter and the policy, and we will read both and tell you where you stand.

Property claims are different because the most important deadline is often written into your policy, not only into the law. Michigan's default time to sue on a contract is six years. But a policy can shorten that time, and courts will enforce the shorter date as written. Rory v Continental Ins Co, 473 Mich 457 (2005). That is why the first thing we look for in any policy is the deadline to sue.

What we help with

Denied home claims. Fire, water, storm, and theft claims that were denied or paid short. The denial letter gives a reason, usually an exclusion, which is a part of the policy that takes certain losses out of coverage. We compare that reason with the actual words in your policy, because the two do not always match.

Fire policy claims. Michigan law sets a minimum time to sue for every fire policy. You get at least one year after the loss to sue, or longer if your policy allows it. The clock pauses from the day you report the loss until the insurance company formally denies it. MCL 500.2833(1)(q).

Appraisal. Appraisal is a process for settling the dollar amount without a lawsuit. Each side picks an appraiser, and the two appraisers pick a neutral umpire. MCL 500.2833(1)(m). Appraisal decides how much the loss is worth, but it does not decide whether the loss is covered. Cantina Enterprises II Inc v Property-Owners Ins Co, 349 Mich App 682, 693-694 (2024).

Car damage after a crash. The mini-tort is a small claim against the at-fault driver for vehicle damage. It lets you collect up to $3,000 for damage your own insurance did not pay. MCL 500.3135(3)(e).

Damage someone else caused. If a person or business damaged your property, that claim is separate from your insurance claim. You have three years to file it. MCL 600.5805(2).

Tell us what happened at askazzo.com, or call 844-ASK-AZZO (844-275-2996). The office is at 33687 Woodward Ave in Birmingham.
Lawyers specialized in
Property damage
We will help you with:
Bring us the denial letter and the policy
Appraisal sets the amount, not the coverage
We tell you honestly if the fight is worth it
Let’s talk
$3,000

The most you can collect from an at-fault driver for vehicle damage your own insurance did not cover, for crashes after July 1, 2020. MCL 500.3135(3)(e).

At least 1 year

A fire policy must give you at least one year after the loss to sue, or longer if the policy says so. The clock pauses from your notice of loss until the insurance company formally denies the claim. MCL 500.2833(1)(q).

30 days

A fire policy generally must pay the loss within 30 days after the insurer gets proof of the amount of loss. There are limited exceptions in the statute. MCL 500.2833(1)(p).

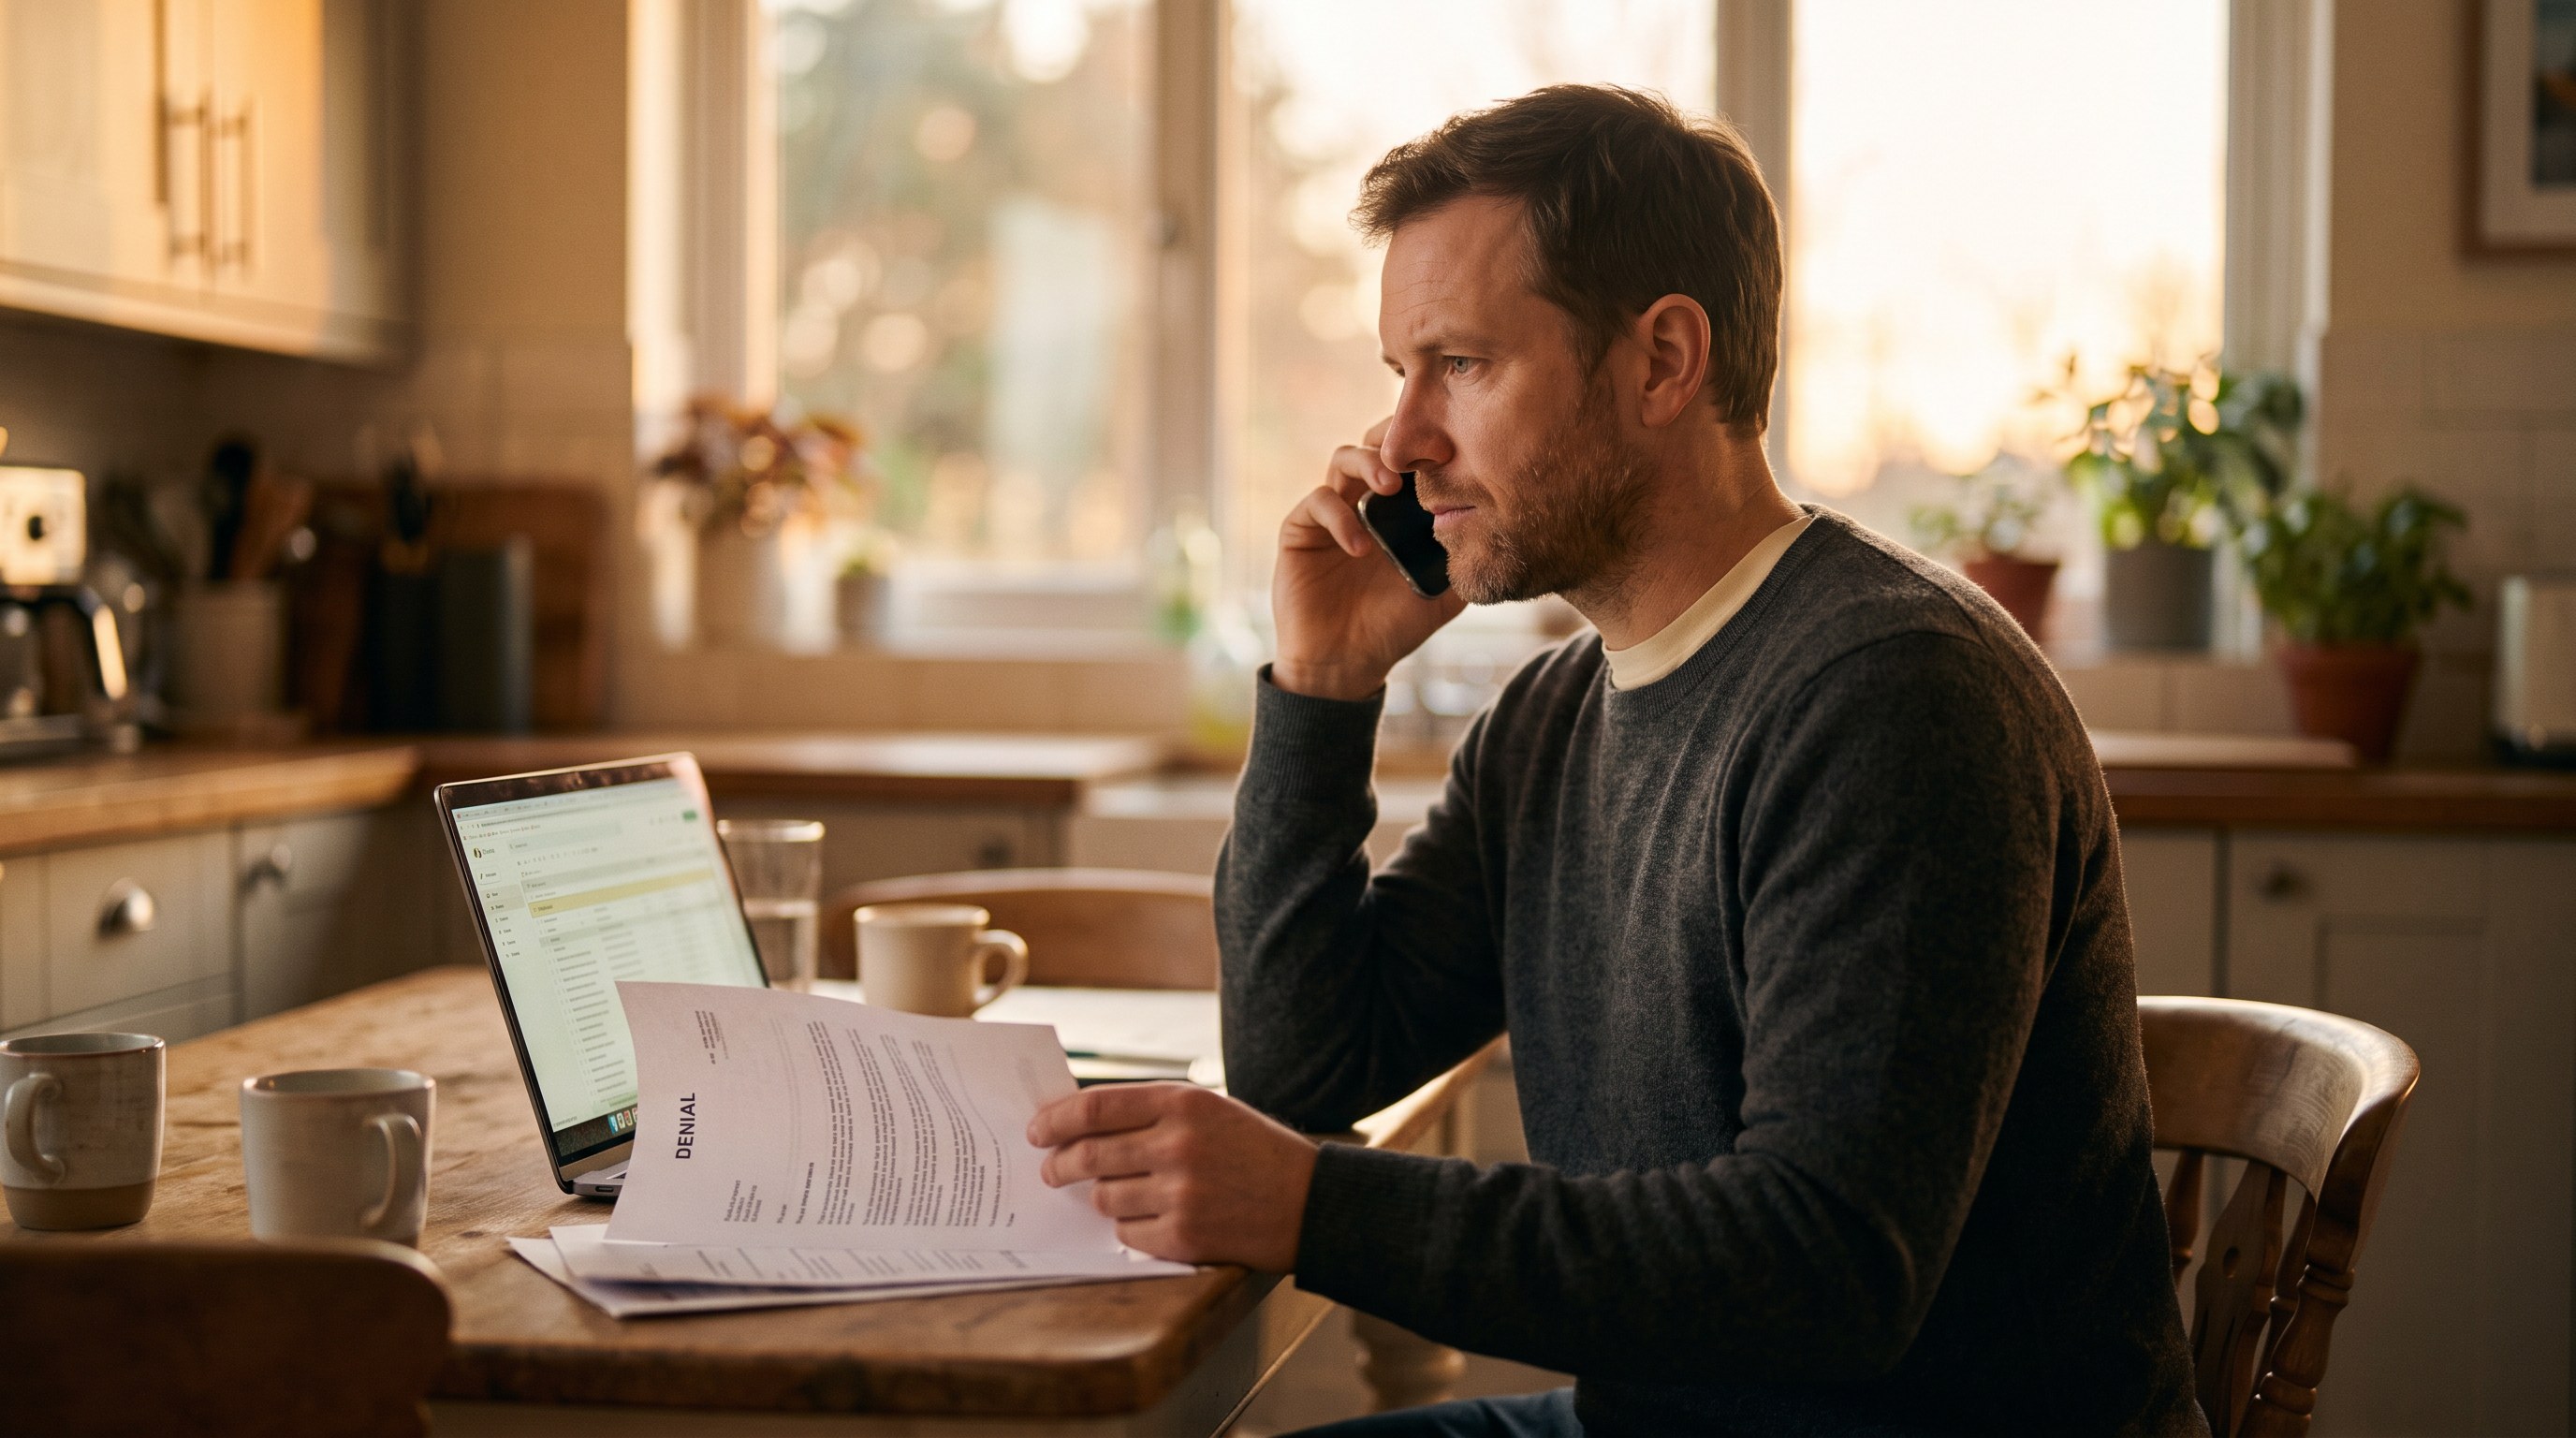
A man at a kitchen table in golden hour light holding an insurance denial letter and making a phone call, a laptop open in front of him.
How this works

Two kinds of claims

Your own insurer. The first-party claim.

A first-party claim is a claim on your own policy, and your policy is a contract. The policy sets the rules about what is covered, what proof you must send, and when you must sue. The default time to sue on a contract is six years. A policy can make that shorter, and courts enforce the shorter time as written. Rory v Continental Ins Co, 473 Mich 457 (2005). For fire policies, the time to sue can never be less than one year after the loss. That time pauses from your notice until a formal denial. MCL 500.2833(1)(q). A policy that tries to remove that pause is void on that point. Smitham v State Farm, 297 Mich App 537 (2012).

The person who caused the damage. The third-party claim.

A third-party claim is against the person or business that caused the damage, and it is based on fault. You have three years after the damage to file it in court. MCL 600.5805(2). After a Michigan car crash, vehicle damage runs through the mini-tort, which pays up to $3,000 for damage your insurance did not cover. MCL 500.3135(3)(e). Two things end a mini-tort claim completely: being more than 50% at fault, or having your car driven without the insurance Michigan requires. MCL 500.3135(4)(a), (4)(e). By law, these cases are filed in the small claims division of district court whenever possible. MCL 500.3135(4)(c).

Appraisal sits in between.

Appraisal settles the amount of the loss, but it does not settle coverage. If the insurance company says part of the claim is not covered, a court decides that question first. Only then can appraisal set the number. Cantina Enterprises II Inc v Property-Owners Ins Co, 349 Mich App 682, 693-694 (2024).

Deadlines

Deadlines

As little as 60 days to send a sworn proof of loss, in some policies. A proof of loss is a signed statement of what you lost and what it is worth. Your policy says when that clock starts. Missing it can cost you the claim unless the insurer waived it. Cantina Enterprises II Inc v Property-Owners Ins Co, 349 Mich App 682 (2024), citing Auto-Owners Ins Co v Gallup, 191 Mich App 181 (1991).

Your policy's deadline to sue. It may be much shorter than six years, and courts enforce it as written. Rory v Continental Ins Co, 473 Mich 457 (2005). Find this date in your policy before you do anything else.

At least one year to sue on a fire policy. The clock pauses from the day you report the loss until the insurance company formally denies it. MCL 500.2833(1)(q). An insurance policy cannot take that pause away, even if its own wording says otherwise. Smitham v State Farm, 297 Mich App 537 (2012).

The clock starts again on a formal denial. That denial has to be clear enough to tell you that court is your next step. Smitham, 297 Mich App at 545. A letter that denies part of a claim may not end the pause for the rest of it. Maksym v Auto-Owners Ins Co, Mich Ct App No. 372827 (Feb 24, 2026).

Three years to sue the person who damaged your property, including a mini-tort claim for your car. MCL 600.5805(2).

Practical advice, not a deadline. Report the loss to your insurance company in writing right away. Take photos before anything is cleaned up or thrown out, and keep damaged items if you can. Save every letter, email, and estimate the insurance company sends you. Do not let appraisal or ongoing talks distract you from the date to sue.

Proof of loss, if your policy sets 60 days
Cantina Enterprises II, 349 Mich App 682 (2024)
5
60 days
Suit on a fire policy, at minimum
MCL 500.2833(1)(q)
33
1 year
Suit against the person who caused the damage
MCL 600.5805(2)
100
3 years
Working with us

Working with us

A named attorney owns the file and calls you back, usually the same day.

1

You call, or you send it.

2

We read the policy and the denial.

We compare the reason in the letter with the actual words in your policy, because sometimes they do not line up.

3

We find your real deadline.

Your policy may shorten the time to sue. We find that date first and plan everything around it.

4

We get the proof of loss in.

We make sure it is signed, complete, and sent on time. Some policies give you as little as 60 days.

5

We push on the number.

We use repair estimates, real sale prices for vehicles like yours, and appraisal when the only fight is the amount.

6

We file before time runs out.

We watch your deadline through every letter and every round of talks. If the claim is small, we point you to small claims court.

Fees

The first consultation is free, and you are under no obligation to hire us. Before we do any work, we explain how the fee works and put it in a written agreement that you sign. Case costs are listed separately, so you know the terms before you decide.

Some property fights are too small to be worth a lawyer after fees. If yours is one of them, we will say so. Then we will point you to small claims court or to appraisal and explain how to start.

Questions

Questions people ask

My insurance company denied my home claim. What can I do?

You can challenge the denial. Start with the letter and find the reason it gives, then read that same part of your policy. If the insurance company still will not pay, you can sue on the policy, but only within the deadline your policy sets. Rory v Continental Ins Co, 473 Mich 457 (2005).

How long do I have to sue my insurance company in Michigan?

Check your policy first, because it may set a short deadline that courts will enforce. Rory v Continental Ins Co, 473 Mich 457 (2005). A fire policy must give you at least one year after the loss. That clock pauses from the day you report the loss until the insurance company formally denies it. MCL 500.2833(1)(q).

When does the clock start again after I report a loss?

On a fire policy, it starts again when the insurance company formally denies the claim. MCL 500.2833(1)(q). That denial has to be clear enough to tell you that court is your next step. Smitham v State Farm, 297 Mich App 537, 545 (2012). A letter that denies part of a claim and asks for more paperwork may not be a formal denial of the rest. Maksym v Auto-Owners Ins Co, Mich Ct App No. 372827 (Feb 24, 2026).

Can an appraisal decide whether my claim is covered?

No, appraisal only decides how much the loss is worth. If the insurance company says the loss is not covered, a court must decide that question first. Cantina Enterprises II Inc v Property-Owners Ins Co, 349 Mich App 682, 693-694 (2024).

What is a proof of loss, and when is it due?

It is a signed, sworn statement of what you lost and what it is worth. Some policies give you as little as 60 days to send it, and the policy says when that clock starts. Missing it can cost you the claim unless the insurer waived it. Cantina Enterprises II Inc v Property-Owners Ins Co, 349 Mich App 682 (2024), citing Auto-Owners Ins Co v Gallup, 191 Mich App 181 (1991). On a fire policy, the insurer generally must pay within 30 days after it receives proof of the amount of loss. MCL 500.2833(1)(p).

Can I make the other driver pay for my car damage?

Yes, up to $3,000 for damage your own insurance did not cover, for crashes after July 1, 2020. MCL 500.3135(3)(e). You recover nothing if you were more than 50% at fault, or if your car was being driven without the required insurance. MCL 500.3135(4)(a), (4)(e). By law, these claims are filed in the small claims division of district court whenever possible. MCL 500.3135(4)(c).

If I win my car damage case in small claims, can I still sue for my injuries?

Yes. Winning a small claims case for vehicle damage does not block a later lawsuit for your injuries from the same crash. Kaiser v Smith, 188 Mich App 495 (1991). The mini-tort statute says the same thing. MCL 500.3135(4)(d).

The Azzo Law storefront office on a Birmingham main street at dusk, warm light in the windows.

Lauren Sitto Azzo leads Azzo Law from 33687 Woodward Ave in Birmingham, with a team behind the work. A denial letter is the insurance company's side of the story, not the last word. Most of these cases come down to what your policy actually says and the date written in it.

Call 844-ASK-AZZO or tell us what happened. Send the denial letter and the policy, and we will tell you plainly where you stand.

Explore other services

Tell us what happened

Answer a few short questions and tell your story from wherever you are. Your answers go straight to the team, and sending them commits you to nothing.