Car accidents and no-fault

Car accidents and no-fault

Most people call the week of the crash, unsure they even have a case. You do not have to know yet.
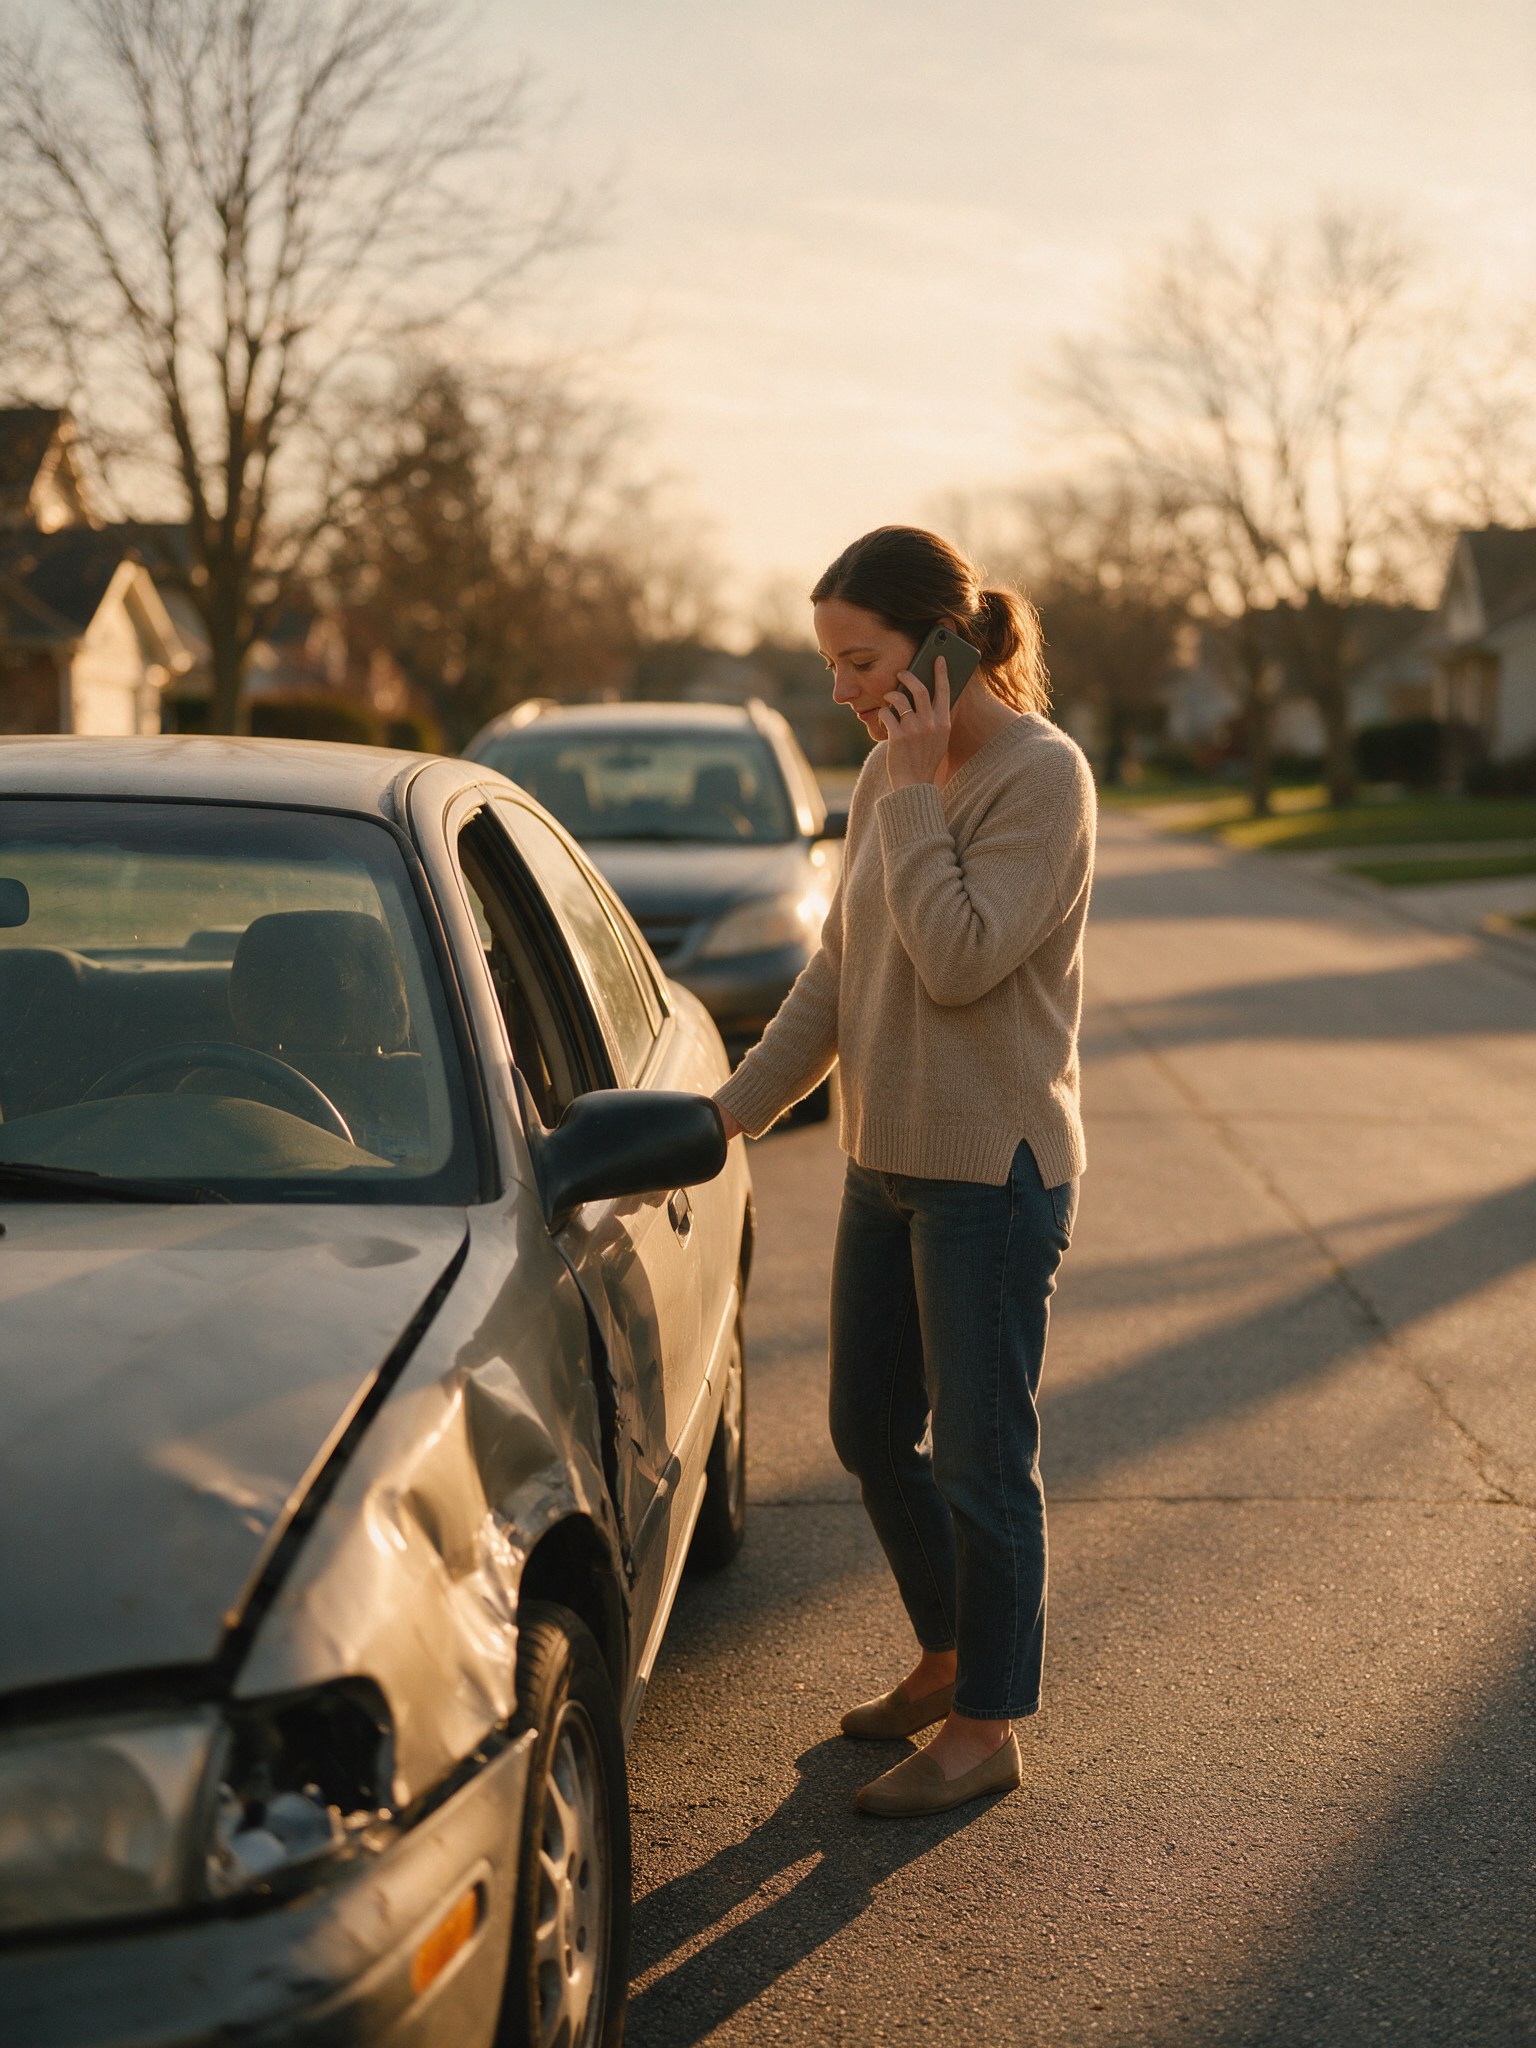
A woman standing beside her damaged car on a quiet residential street in late afternoon light, making a phone call.

In Michigan your own insurer pays first. We handle that claim and the one against the at-fault driver as a single case.

Michigan splits your crash into two cases. One runs against your own policy and pays medical care and lost wages no matter who caused the wreck. The other runs against the driver who hit you, and it only opens once your injury clears the threshold in MCL 500.3135. Two insurers, two sets of deadlines, and neither covers what the other misses.

What no-fault actually pays

Medical care. Reasonable and necessary treatment, paid off a fee schedule set at 190% of the Medicare amount for treatment after July 1, 2023. MCL 500.3157(2)(c).

Wage loss. 85% of what you lost, for three years, capped at $7,201 in any 30-day period. MCL 500.3107(1)(b).

Replacement services. $20 a day for the household work you can no longer do, for three years. That figure has not moved since 1973. MCL 500.3107(1)(c).

Attendant care at home. Paid even when a spouse, sibling, child, or parent provides it, up to 56 hours a week unless the insurer agrees to more. MCL 500.3157(10), (11).

Survivor's loss. The same $7,201 cap for three years. MCL 500.3108.

Funeral and burial. What the policy sets, never below $1,750 and never above $5,000. MCL 500.3107(1)(a)(ii).

From the at-fault driver: pain and suffering once the threshold is met, economic loss above your PIP ceiling under MCL 500.3135(3)(c), and up to $3,000 in vehicle damage under the mini-tort at MCL 500.3135(3)(e).

Tell us what happened at askazzo.com, or call 844-ASK-AZZO (844-275-2996). The office is at 33687 Woodward Ave in Birmingham.
Lawyers specialized in
Car accidents and no-fault
We will help you with:
One attorney handles the no-fault claim and the lawsuit
Your no-fault benefits do not wait on a fault decision
Injury cases run on contingency
Let’s talk
$7,201 per 30-day period

The cap on no-fault wage loss for accidents on or after October 1, 2025. It replaces 85% of what you were earning, for up to three years. MCL 500.3107(1)(b).

One year

To put your insurer on written notice or file for no-fault benefits. MCL 500.3145(1).

Unlimited

The level that applies by operation of law when no effective selection was made and no premium-based presumption applies. MCL 500.3107c(4). Most drivers hold one of three levels: $250,000, $500,000, or unlimited. A fourth level of $50,000 exists, available only where the named insured is enrolled in Medicaid and the household members carry qualified health coverage, Medicaid, or their own PIP. MCL 500.3107c(1)(a).

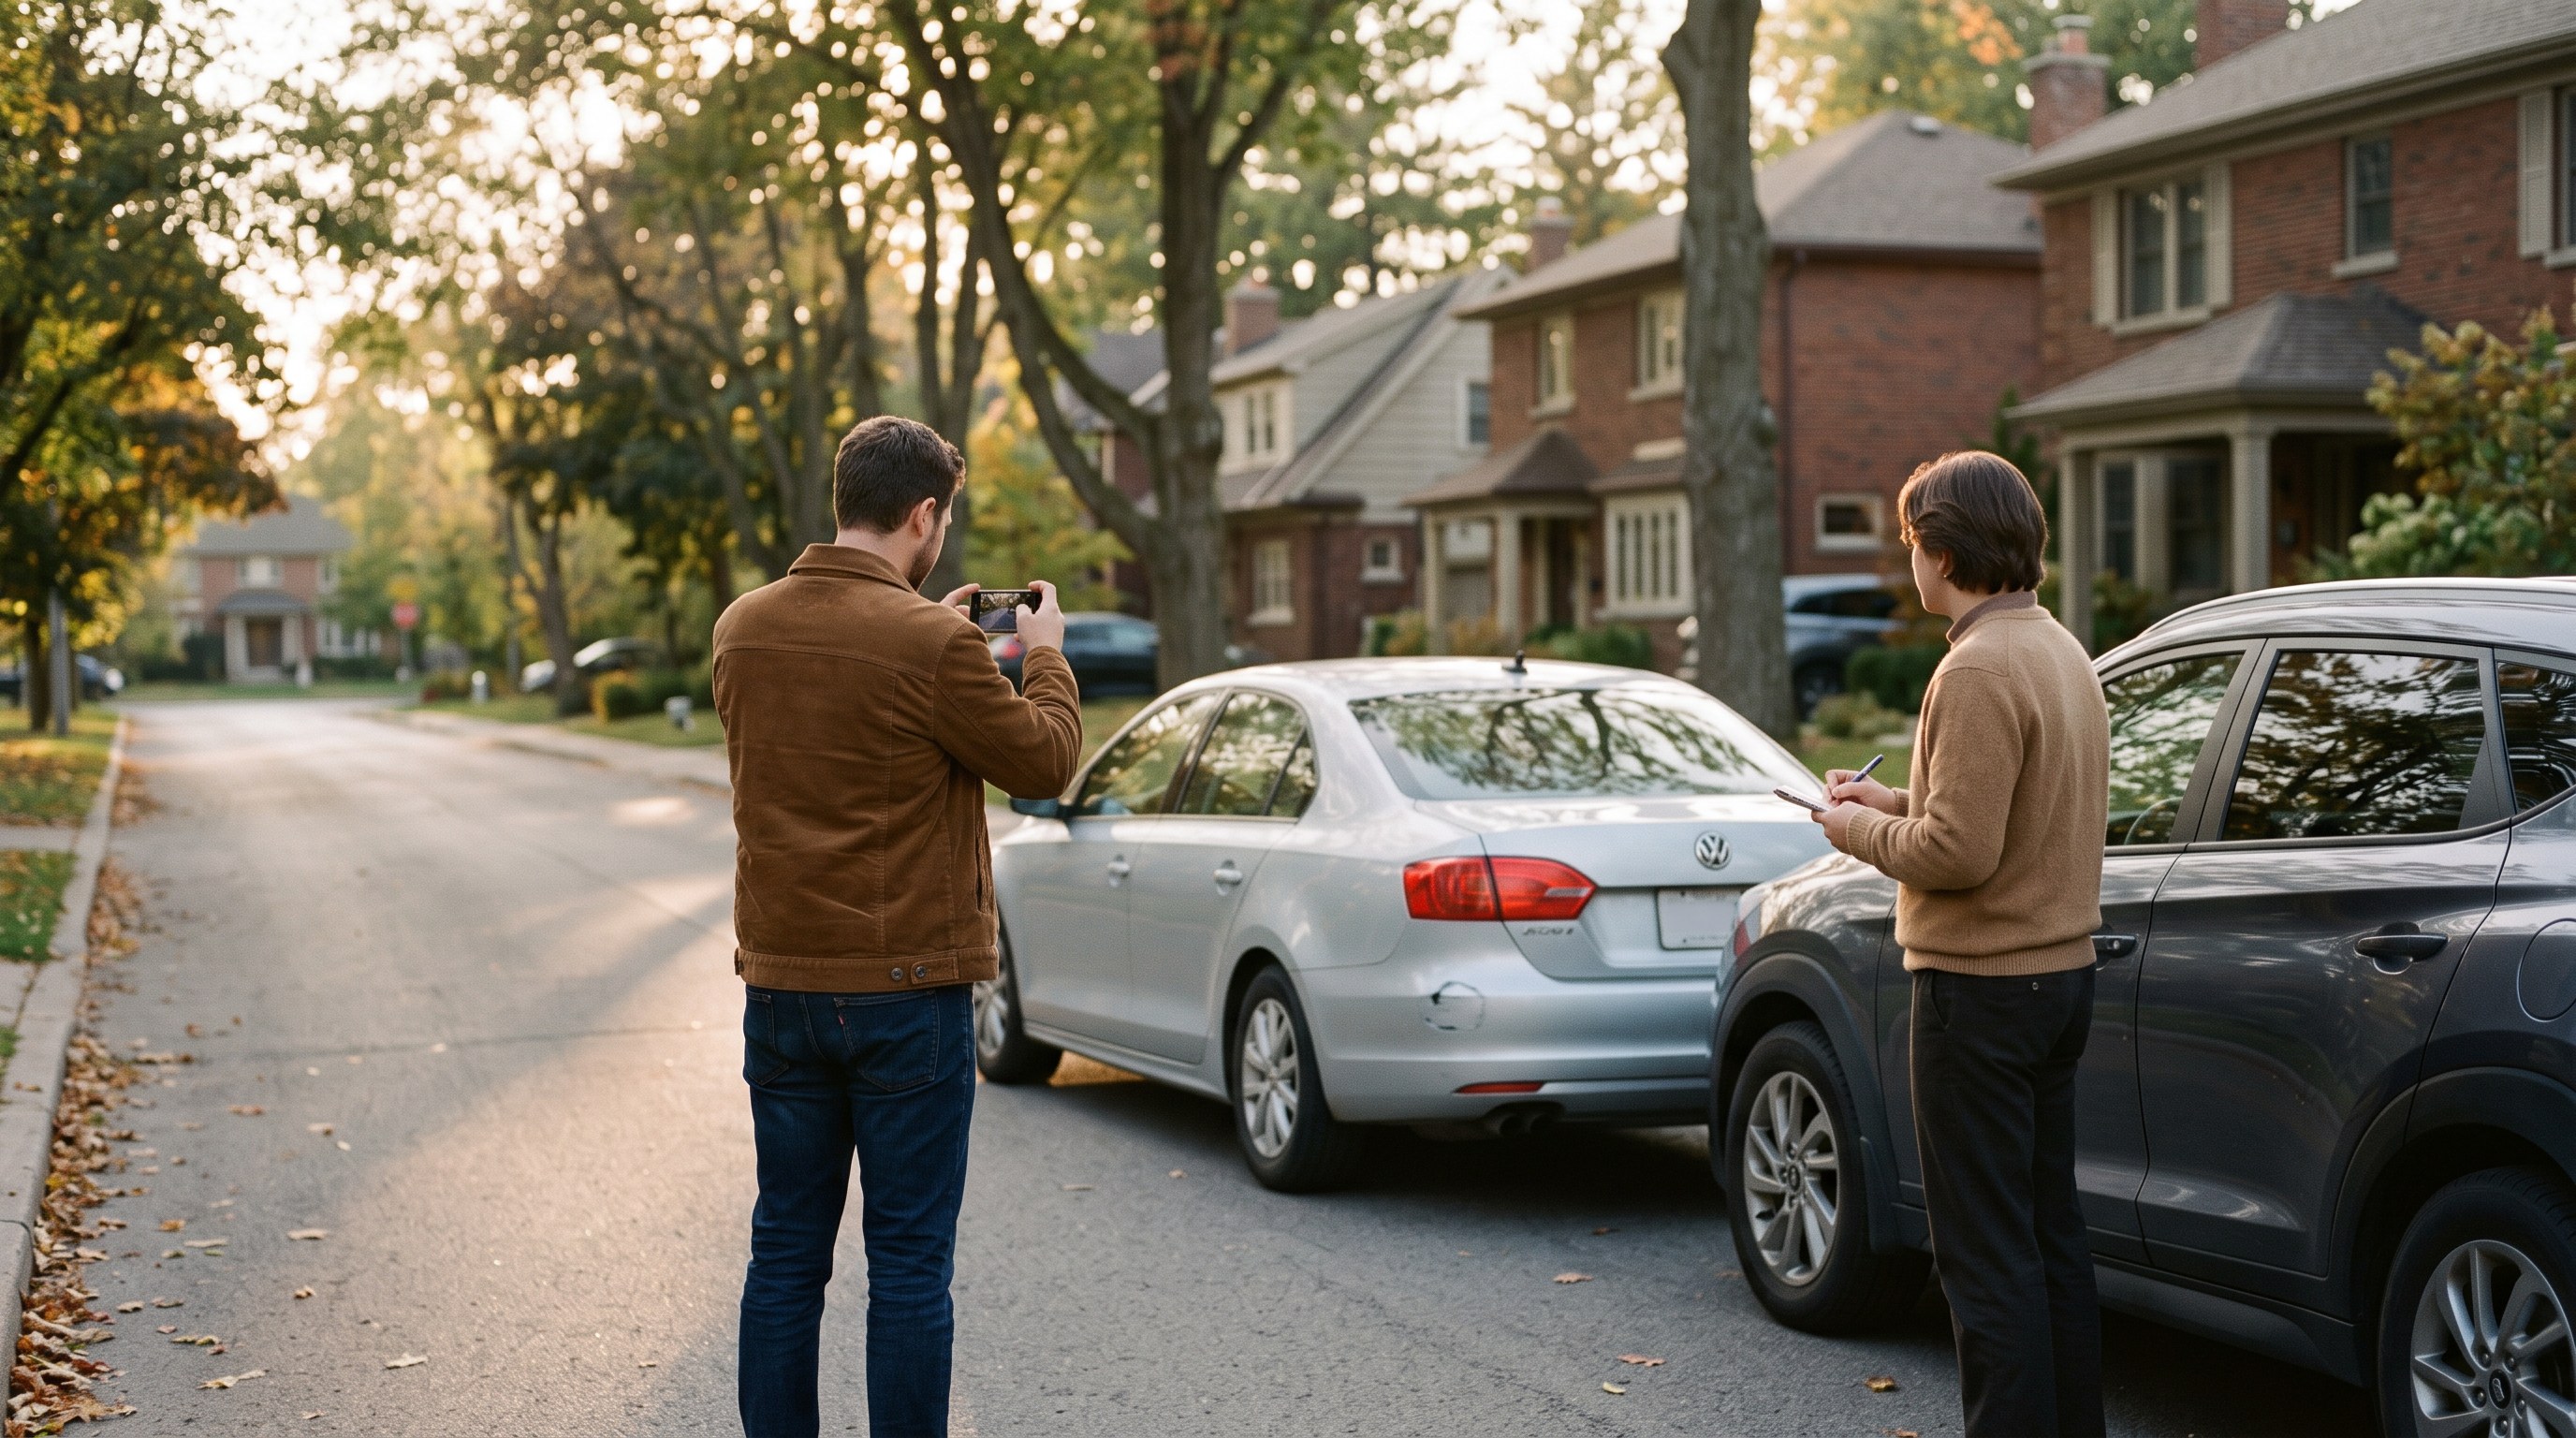
Two drivers on a quiet suburban street at golden hour calmly exchanging information, one photographing the other car with a phone.
How this works

Two claims, two insurers

Your own insurer. The first-party claim.

Your no-fault coverage pays whether the crash was your fault or not. No fault finding, no argument about who ran the light. It covers medical care, wage loss, replacement services, and attendant care. What it can pay is capped by the coverage level someone in your household selected under MCL 500.3107c. Most people do not know which level they hold. That number is the ceiling, so we find it first.

The driver who hit you. The third-party claim.

Fault-based, and it does not open automatically. Michigan requires death, permanent serious disfigurement, or serious impairment of body function. MCL 500.3135(1). Serious impairment has three parts under MCL 500.3135(5): objectively manifested, involving an important body function, and affecting your general ability to lead a normal life. No minimum length of time. Your recovery is reduced by your share of fault, and above 50% you recover no noneconomic damages at all. MCL 500.3135(2)(b). Excess economic loss under MCL 500.3135(3)(c) runs on its own track.

Deadlines

Deadlines

One year from the crash to give written notice of injury or file for benefits. The notice carries the claimant's name and address, the injured person's name, and the time, place, and nature of the injury. MCL 500.3145(1), (4).

One year back. Even with a timely case, you recover nothing for loss incurred more than one year before the day you filed. MCL 500.3145(2). Every month you wait is a month you cannot get back.

The clock stops between the day you make a specific claim for payment and the day the insurer formally denies it. MCL 500.3145(3).

Three years to sue the at-fault driver, and three years for the mini-tort vehicle damage claim. MCL 600.5805(2).

One year for property protection benefits. MCL 500.3145(5).

A child gets one year past their eighteenth birthday for the tort claim. MCL 600.5851(1). That extension does not reach the one-year-back rule. Joseph v Auto Club, 491 Mich 200 (2012). A parent can win the lawsuit and still lose years of paid attendant care.

Written notice of injury, or a claim for benefits
MCL 500.3145(1)
33
1 year
The one-year-back rule on what you can recover
MCL 500.3145(2)
33
1 year
Suit against the at-fault driver
MCL 600.5805(2)
100
3 years
Working with us

Working with us

A named attorney owns the file and calls you back, usually the same day.

1

You call, or you send it.

2

We pull the coverage.

Your policy, the household policies, the other driver's policy, and the level selected under MCL 500.3107c. That level is the ceiling.

3

We put the notice in writing.

The one-year clock under MCL 500.3145(1) stops being a threat the day it lands.

4

We build the record.

Treatment, restrictions, and the attendant care and replacement services logs. Carriers pay on the log and most people never keep one.

5

We take the insurer calls.

Independent medical exams, cutoff letters, recorded statement requests.

6

We evaluate the third-party case against MCL 500.3135

We file inside the three years if the threshold is met.

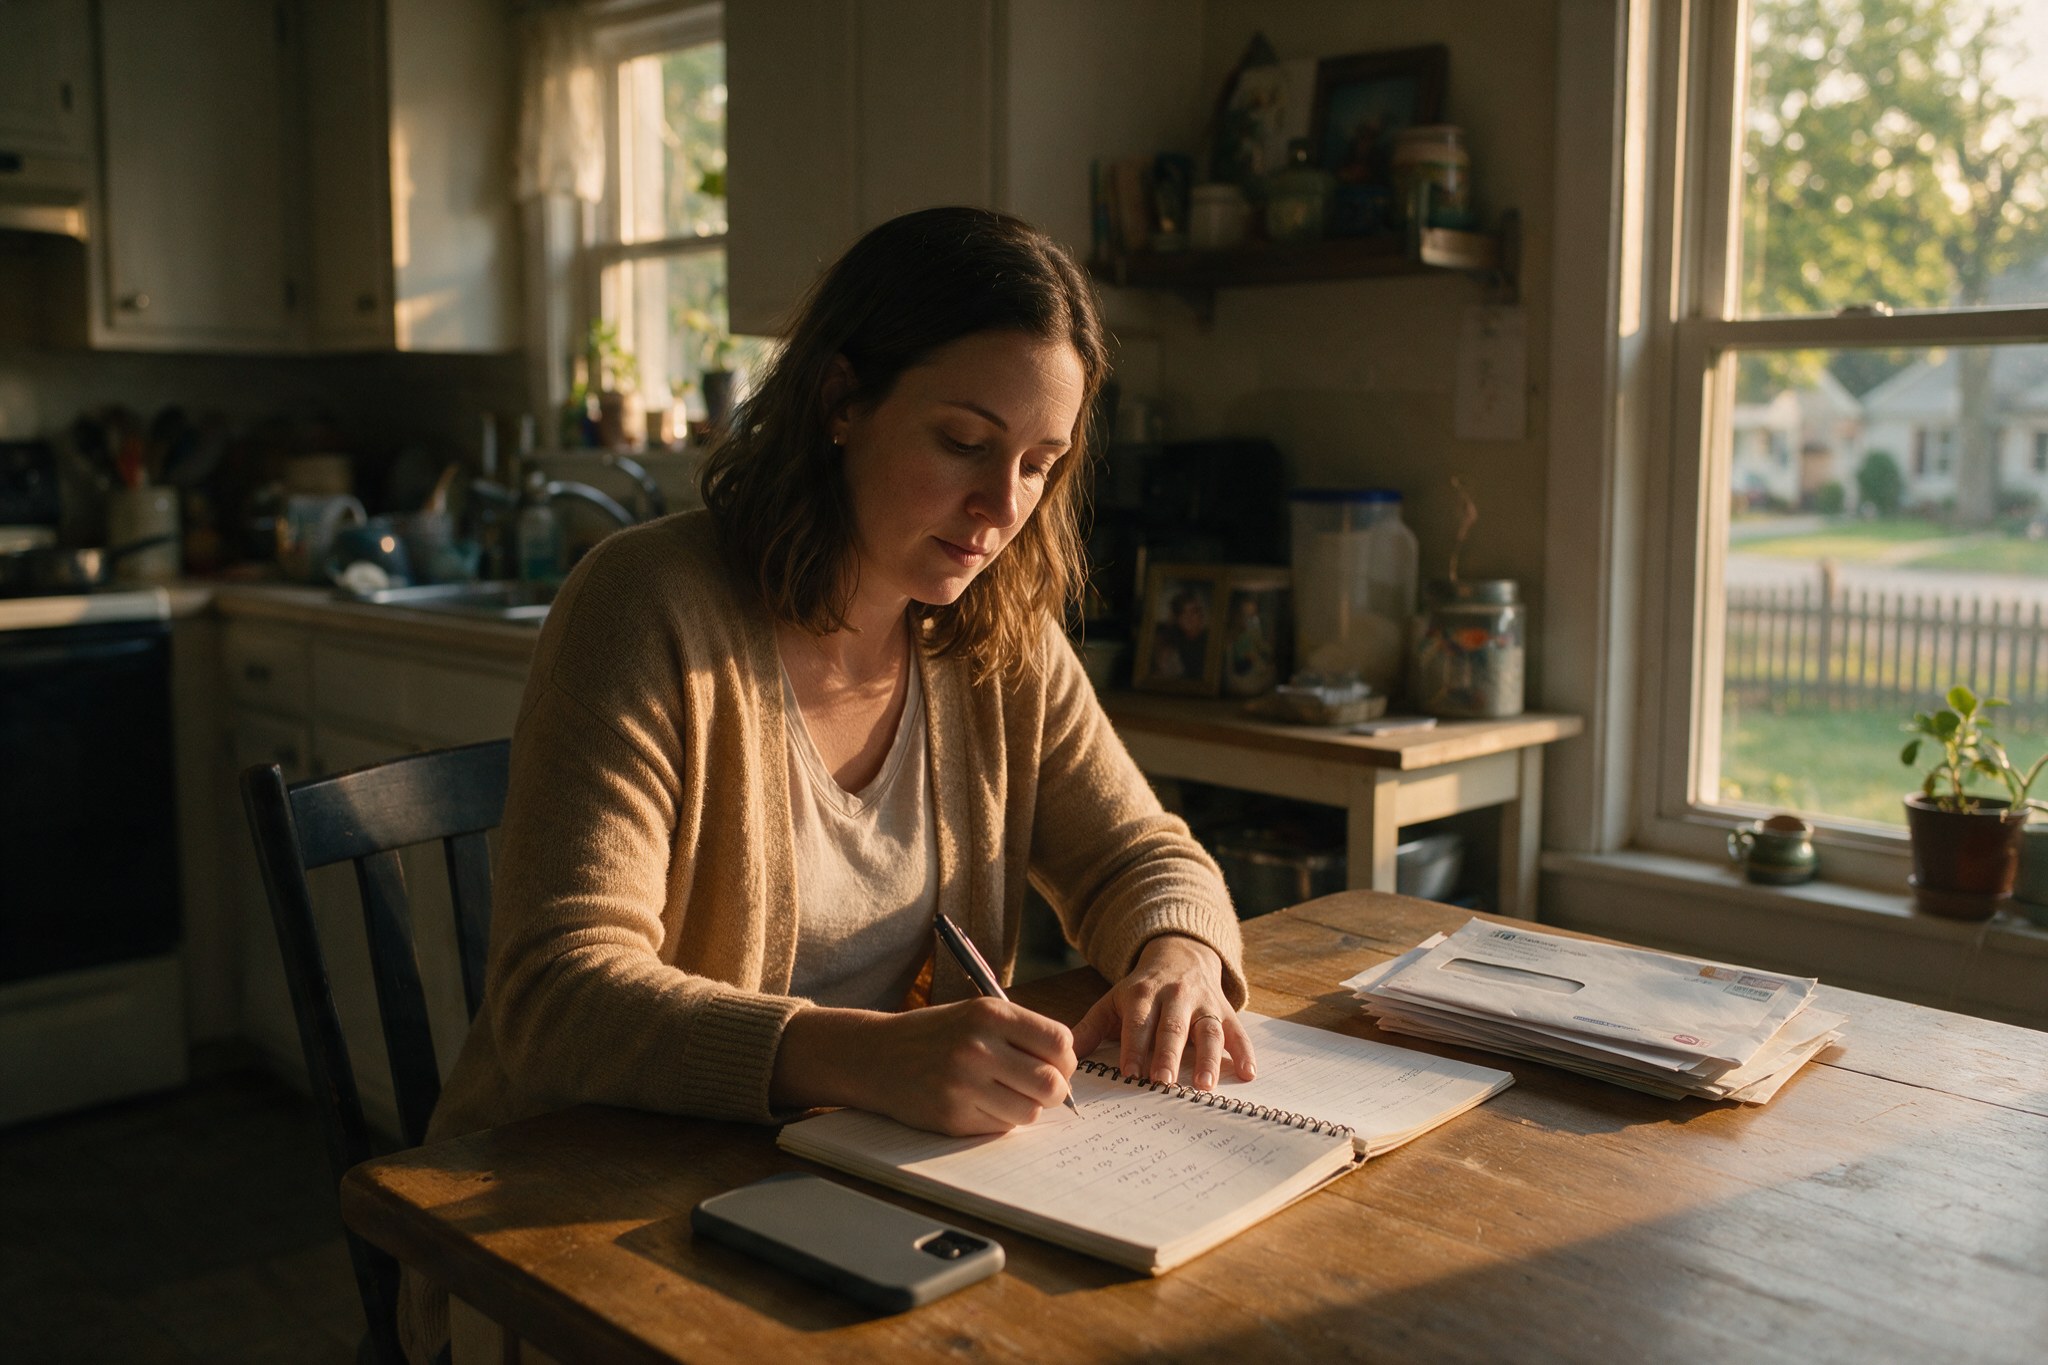
A woman at her kitchen table in late afternoon light writing appointment dates and mileage in a notebook, medical billing envelopes stacked beside her.

Fees

No Fee Unless We Win.

Crash cases run on contingency. No attorney fee unless we recover for you, and the fee comes out of the recovery at a percentage set in a written agreement you sign before we start. Case costs are itemized separately. The consultation costs nothing, and if the case is not worth pursuing we say so instead of signing you up.

The order it runs in

  1. Recovery
  2. Case costs
  3. Attorney fee
  4. Medical liens
  5. What reaches you
Questions

Questions people ask

Who pays my medical bills after a Michigan car accident?

Your own auto insurer pays first, through your no-fault PIP coverage, no matter who caused the crash. How much it pays is capped by the level someone in your household chose under MCL 500.3107c. Most drivers hold $250,000, $500,000, or unlimited. A $50,000 level is available only to a named insured enrolled in Medicaid whose household members carry qualified health coverage, Medicaid, or their own PIP. Where no effective selection was made and no premium-based presumption applies, unlimited applies by operation of law. MCL 500.3107c(4).

How long do I have to file a claim after a car accident in Michigan?

One year from the accident to give your insurer written notice of injury or file for no-fault benefits, and three years to sue the at-fault driver. MCL 500.3145(1) and MCL 600.5805(2). Two clocks, two parties, and meeting one does nothing for the other.

What is the one-year-back rule?

It caps how far back your damages reach, and it is not a filing deadline. Under MCL 500.3145(2) you cannot recover any loss incurred more than one year before the day you filed suit. You can file on time and still lose two years of unpaid benefits.

Can I sue the driver who hit me in Michigan?

Only if your injury meets the threshold in MCL 500.3135(1): death, permanent serious disfigurement, or serious impairment of body function. Serious impairment has to be objectively manifested, involve an important body function, and affect your general ability to lead a normal life. MCL 500.3135(5).

What happens if the crash was partly my fault?

Your recovery is reduced by your share of fault, and above 50% you recover no noneconomic damages at all. MCL 500.3135(2)(b). Your first-party no-fault benefits are paid regardless of fault.

My insurer denied my PIP claim. Now what?

You can sue your own insurer. Benefits go overdue 30 days after the carrier has reasonable proof of loss, and overdue benefits carry 12% simple interest a year. MCL 500.3142(2), (4). Bring the denial letter. The stated reason and the real reason are often different.

How much does no-fault pay for lost wages?

85% of the income you lost, for up to three years, capped at $7,201 in any 30-day period for accidents on or after October 1, 2025. MCL 500.3107(1)(b). The cap resets every October 1, and your accident date picks the number.

The Azzo Law storefront office on a Birmingham main street at dusk, warm light in the windows.

Lauren Sitto Azzo leads Azzo Law from 33687 Woodward Ave in Birmingham, with a team behind the work. A carrier does not value your injury. It values your file: the treatment record, the gaps in it, the logs nobody kept. We build the file knowing what the adjuster reads first.

Call 844-ASK-AZZO or tell us what happened. We will read the denial letter, pull your coverage, and tell you what you are actually looking at.

Explore other services

Tell us what happened

Answer a few short questions and tell your story from wherever you are. Your answers go straight to the team, and sending them commits you to nothing.